Section 351 Exchange

Turn concentrated holdings into a diversified ETF — tax-efficiently.

A Section 351 ETF Exchange offers a tax-deferred pathway to transition legacy stock positions into an ETF — without triggering capital gains — and our team will provide support through every step of the process.

Key benefits
01
Diversify
Transfer concentrated, low-basis positions into a diversified ETF
02
Defer taxes
Avoid triggering capital gains at the time of transfer
03
Defend your gains
Original cost basis and holding period carry over to ETF shares
Who benefits most

Is a 351 Exchange right for you?

Who benefits
  • UHNW investors
  • Families with large embedded gains
  • Clients with concentrated employer or legacy positions
  • Advisors serving clients with complex taxable portfolios
The problem

Concentrated, low-basis positions create compounding challenges:

  • Large exposures to a single stock increase portfolio risk
  • Selling triggers an immediate tax bill
  • Direct indexing and megacap performance amplify unintended overweighting
The solution

A Section 351 Exchange provides a tax-deferred path to diversify concentrated, low-basis holdings while restoring portfolio alignment — all in one mechanism.

Tax-free today vs. tax-efficient tomorrow

Tax-free today

Section 351 Exchange

  • Transfer appreciated securities without recognizing capital gains at transfer
  • Original cost basis and holding period carry over to received ETF shares
  • Avoid concentration legacy without a taxable event
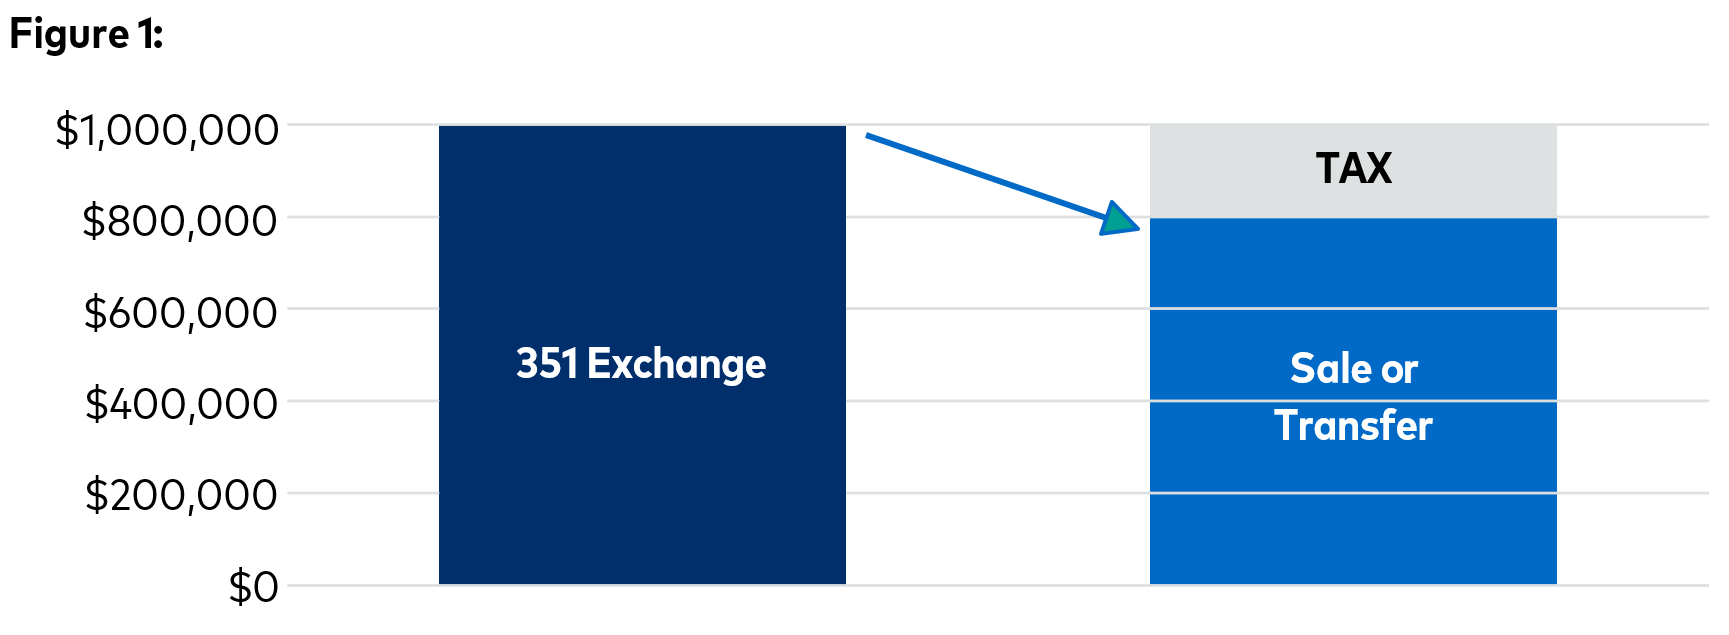
Figure 1: Section 351 Exchange tax savings illustration

Assumptions: Long-Term Capital Gains + Net Investment Income Tax Rate: 23.8%.

Tax-efficient tomorrow

ETF's continuing tax advantages

  • In-kind creations and redemptions limit fund-level capital gains and taxable distributions
  • Investors control when gains are realized — typically when they sell ETF shares
  • ETFs help defer tax drag after-tax compounding over time
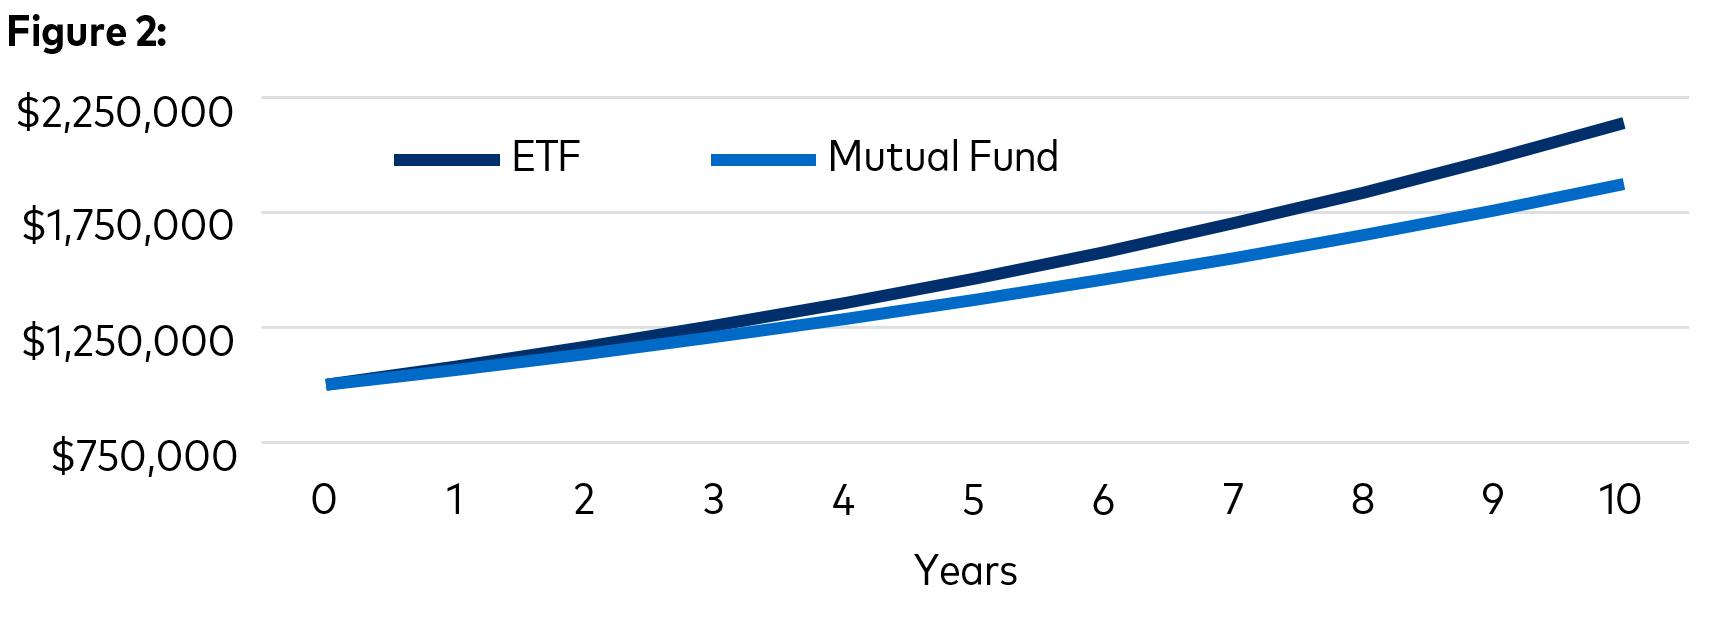
Figure 2: ETF versus mutual fund after-tax comparison

Annual gross return: 8%. ETF annual taxable distribution: 0.5% of NAV. Mutual fund annual taxable distribution: 6% of NAV.

The process

Converting with confidence: the 351 timeline

We've designed a clear, step-by-step process to make your 351 Exchange as seamless as possible.

Step 1
6–8+ weeks before
Initial review
  • Review current holdings
  • Discuss goals with advisor
  • Confirm timing
Step 2
4–6 weeks before
Portfolio assessment
  • Submit full holdings file
  • Ensure diversification requirements
  • Identify adjustments
Step 3
2–4 weeks before
Preparation & documentation
  • Finalize agreements
  • Coordinate with custodian
  • Confirm eligibility
Step 4
Launch date
ETF launch & exchange
  • Contribute approved securities
  • Receive ETF shares at NAV
  • Defer capital gains taxes
Step 5
Post launch
Ongoing ownership
  • ETF begins trading
  • Maintain liquidity & diversification
  • Taxes deferred until sold

Everything you need to know

Comprehensive resources to help you understand the 351 Exchange.

The concentration challenge
Diversify. Defer Taxes. Defend Your Gains.
About 351 Exchanges
Download Quick Take →
The concentration challenge
Paths to Reduce Concentration
The primary strategies investors use
Download Quick Take →
The tax tradeoffs
Tax-Free In, Tax-Efficient Within
Preserving investable capital
Download Quick Take →
The tax tradeoffs
Tax-Free Today vs. Tax-Efficient Tomorrow
By the numbers comparison
Download Quick Take →
Evaluating
From Strategy To Execution
A simple 3-step process
Download Quick Take →
Implementation
How Section 351 Exchanges Affect Taxes
Detailed overview, requirements, portfolio examples
Download Resource →
FAQ

Common questions

Answers to the most frequently asked questions about Section 351 exchanges.

What is a Section 351 Exchange?
Section 351 of the Internal Revenue Code allows investors to transfer appreciated assets into an ETF without triggering capital gains taxes at the time of transfer — similar to a 1031 exchange in real estate. Investors receive ETF shares in exchange for their contributed securities, deferring taxes on unrealized gains.
What are the diversification requirements?
To qualify, your portfolio must meet these criteria: no single issuer's securities may exceed 25% of the portfolio's value; the top five issuers' securities may not exceed 50% of the portfolio's value in total; and contributed positions must align with the ETF's investment mandate.
What documents will I need?
Required documents include: Excel file of holdings with tax lot information, Custodian Letter of Authorization (LOA), month-end brokerage statement, and Subscription Agreement.
Who should I contact to get started?
Contact our Product Strategy team to discuss your options and determine next steps.

Ready to explore your options?

Our team is here to answer your questions and determine if a 351 Exchange is right for you and your clients.

Contact us →

Important Disclosures: This information is not to be relied on as legal, tax, business, investment, accounting, or any other advice. Recipients should seek their own independent financial and tax advice. Investing involves inherent risks, and any particular investment is not suitable for all investors; there is always a risk of losing part or all of your invested capital. No statement herein should be interpreted as an offer to sell or the solicitation of an offer to buy any security. Any timelines referenced herein are provided for illustrative purposes only and may be modified at any time.

External website

You are now leaving the Polen Capital website.

By clicking on the link you have selected, you will be redirected to a third-party website that is not controlled by Polen Capital. Please note that we are not responsible for the content, privacy policies, or security of the third-party website. We encourage you to review the terms and conditions, as well as the privacy policy of the third-party website.

Continue to Site
UCITS funds — Important information

Select your location and investor type.

Polen Capital Investment Funds PLC is registered for sale in certain countries only. The information on the following pages is not intended for persons in jurisdictions where the funds are not registered, or for US persons.

Your selection is saved for this browser session.